Buying a Historic Home in New York: What to Know First
Back to the NYC Real Estate Blog
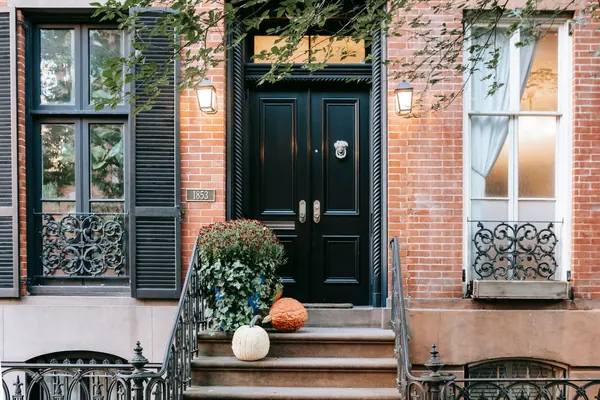
Buying a historic home in New York means you can’t freely change the exterior. An individual landmark or a house in a historic district needs approval for outside work. In return, a 20% New York State tax credit can offset the cost of qualified repairs, and the house often holds its value well.
We’ve represented buyers in brownstones and Old Village houses. The ones who are happy a year later all did one thing: they priced the maintenance, not the mantel. Here’s the trade-off, straight.
Pros and cons of buying a historic home
The charm is on the listing, and the maintenance is in the basement. A historic home gives you craftsmanship you can’t buy new and a block that won’t change around you. It often carries a resale premium too, as buyers tire of thin-walled new construction.
The costs are the flip side. Old systems, lead paint, knob-and-tube wiring, settling, and slate or copper roofs that cost real money. You also give up some control over how the house looks. For most buyers the math works, but only if the inspection and the reserve are honest.
Historic district rules in NYC
Is the house an individual New York City landmark, or inside one of the city’s historic districts? Then the Landmarks Preservation Commission has a say in exterior work. New windows, a new door, facade repair, a rooftop addition: each needs a permit or a Certificate of Appropriateness first.
You can repaint, but the Landmarks Commission would like a word about the color on a designated storefront or ironwork. Interior work is generally free unless the interior itself is landmarked, which is rare. Outside New York City, the State Historic Preservation Office serves as the registrar, and local landmark boards vary from town to town. Our buying process guide covers the standard due diligence you’d add on top of this.
The New York historic home tax credit
New York State offers a Historic Homeownership Rehabilitation Credit worth 20% of qualified rehabilitation costs. To qualify:
- You own the house and live in it.
- It’s on the State or National Register, individually or as a contributing building in a listed district.
- It sits in a qualifying census tract.
- Your qualified costs total at least $5,000, with at least 5% on exterior work.
- The State Historic Preservation Office approves the work before it starts.
As of January 1, 2025, the annual cap dropped to $25,000 per home, and it’s no longer refundable for lower-income filers. The separate federal 20% historic credit applies only to income-producing property, so it doesn’t cover an owner-occupied home.
| New York State credit | Federal credit | |
|---|---|---|
| Rate | 20% of qualified costs | 20% of qualified costs |
| Annual cap | $25,000 per home (since 2025) | No per-home cap |
| Covers an owner-occupied home | Yes | No, income-producing only |
The paperwork is not optional, and neither is the accountant. Have your real estate attorney and a preservation-savvy accountant model this before you count on it. The closing cost calculators help you fold the net repair cost into the deal.
Owning a landmarked home
Day-to-day, a landmarked home is a normal home. The difference shows up when you want to change the outside. You don’t own the facade so much as look after it, and the paperwork for exterior work takes weeks to months, not days.
The upside of that constraint is that your neighbors face it too, so the streetscape you bought into stays intact. Ken Lyon, a historic preservation officer in Palm Springs, put the responsibility plainly: “There is a responsibility in owning a historically designated home in terms of maintenance and upkeep, and honoring aspects of the house that make it significant.” That’s a California voice, but the principle travels.
Financing and insuring an older house
A historic home may need a renovation loan rather than a standard mortgage if it isn’t move-in ready. Lenders and appraisers treat older systems cautiously. The inspector will find things; that’s the job. On a house over a century old, a general inspector plus a structural engineer is money well spent.
Insurance also runs higher because replacing hand-carved trim or a slate roof to code costs more than a builder-grade equivalent. Get an insurance quote before you’re in contract, not after.
What we tell buyers before they fall for a brownstone
Budget for the boiler you can’t see, not the mantel you can. Walk the house with an inspector and, for anything old and large, a structural engineer. Ask the seller for records of past work and any Landmarks approvals, because unpermitted exterior changes become your problem to unwind.
With a real repair reserve and honest insurance priced in, a historic home in New York is one of the better long-term buys around. A commission rebate is a reasonable way to seed that first-year repair fund.
Common questions
Can I renovate a historic home in New York? Yes. Exterior changes to a landmark or a home in a historic district need approval first: the NYC Landmarks Preservation Commission in the city, a local board elsewhere. Interior work is usually unrestricted.
Is there a tax credit for buying a historic home in New York? There’s credit for rehabilitating one. The New York State Historic Homeownership Rehabilitation Credit is 20% of qualified costs. It’s capped at $25,000 per year since 2025 and requires State Historic Preservation Office approval before work begins.
Are historic homes a good investment? Often, yes. They tend to hold value and sit in stable neighborhoods. The risk is deferred maintenance on expensive systems, so the inspection matters more than usual.
Do I need a special mortgage for a historic home? Only if it needs work to be livable, in which case a renovation loan may fit. A sound historic home finances like any other, though appraisers and insurers scrutinize older systems.
Nicole Fishman Benoliel co-founded NestApple in 2017. She's a lawyer admitted to the New York bar - her law degree is from La Escuela Libre de Derecho in Costa Rica, with further study at IE Business School in Madrid and an LLM from Fordham in New York. She does not act in a legal capacity at NestApple; every client is referred to an attorney who handles real estate deals full time.