What Is a Patio Home?
Back to the NYC Real Estate Blog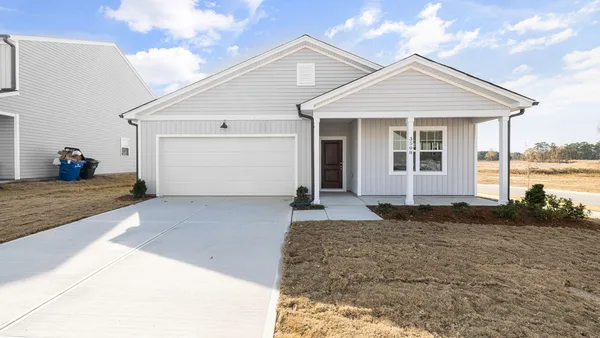
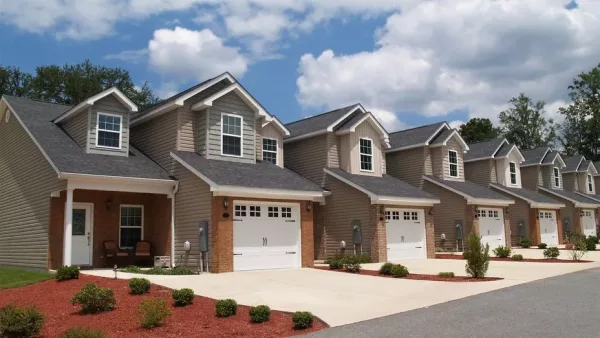
A patio home is a small single-family house on a zero lot line: it sits directly against at least one boundary of its plot, inside a development run by a homeowners association. You own the house and the land under it. The association controls what happens outside your walls, and in Connecticut it owes you 19 disclosure items first.
We buy in Westchester and Connecticut where these developments are common, and the association documents are where nearly every unpleasant surprise lives.
Zero lot line is the actual definition
The name promises a patio, which is the least useful thing about it and occasionally not even there. The defining feature is the lot.
A conventional house sits in the middle of its plot with setbacks on all four sides. A patio home gives up one or more of those setbacks and sits flush against the boundary. That frees the remaining space into one usable yard, rather than four strips nobody walks on.
That’s the trade. You lose the wraparound garden and get one courtyard you’ll actually use, plus a smaller footprint to heat, insure and maintain.
There’s a consequence of the zero line that listings never mention. One owner explains it better than any brochure: “your property ends right at your house’s wall. Often, there aren’t windows on the zero lot line wall. Also, you are almost certainly granted an ‘easement’ to go in the neighbor’s backyard (after obtaining permission) in order to perform any required maintenance.”
Read that twice. Painting or repairing one wall of your own house means standing on someone else’s land, by arrangement. It works fine with a reasonable neighbour and becomes a genuine problem without one.
What you own, and what you only think you own
This is where the previous version of this page was wrong, and where most descriptions still are, cheerfully. You own the structure and the land under it. That does not mean you control it.
| You | The association | |
|---|---|---|
| The house and its interior | own it | nothing |
| The land under the house | own it | nothing |
| Roof and siding | own it, usually | may set the colour and the material |
| Lawn and planting | own it | frequently maintains it, and bills you |
| Snow, gutters, drives | own them | frequently maintains them, and bills you |
| Pool, clubhouse, paths | no | owns and runs them |
| What you may build | own the right, in theory | approves or refuses it, in practice |
The last row is the one people discover late. A fence, a shed, a satellite dish or a different front door can all require approval. The standards are set by a board of your neighbours.
None of that is a reason to avoid one. It’s a reason to read the covenants before you bid, not after, which is what having somebody represent you is for.
Patio home, townhouse, condo: the differences that matter
These three get used interchangeably in listings and they are three different legal animals.
| Patio home | Townhouse | Condo | |
|---|---|---|---|
| Structure | usually detached, on a zero lot line | attached, shares walls | a unit in a building |
| You own the land | yes | yes, the footprint | no |
| Typical height | one storey, sometimes one and a half | two to four | varies |
| Exterior upkeep | often the association | usually you | always the association |
| Where you find them | planned suburban developments | cities and older suburbs | everywhere |
A townhouse in New York City is a whole building you own outright, often with a rental unit in it. Nobody maintains anything for you. A patio home is nearly the opposite: less house, less responsibility, more rules.
What insurance looks like
Here’s a difference that costs money quietly, which is the most expensive way for money to go. A condo owner insures the inside of their unit and the building’s policy covers the rest. A patio home owner insures the whole house, because they own the whole house.
So you need a standard homeowner’s policy, not the cheaper condo version, even though the association handles the lawn. The association’s own policy covers the clubhouse and the common land, and it does not extend to your roof.
Two things are worth asking before you buy. Whether the association carries a master policy at all, and what its deductible is. A large deductible gets passed to owners after a storm, and both answers are in the documents.
Reading the association documents, which is the actual work
Every patio home purchase comes with a stack of paper that most buyers skim, sign, and meet again two years later under considerably worse circumstances. It’s the most valuable hour in the whole transaction, and here’s what to look for.
| Document | What you’re checking |
|---|---|
| Covenants (CC&Rs) | What you may change, build, park or rent out |
| Bylaws | How the board is elected and how it makes decisions |
| Budget | What the dues actually pay for, line by line |
| Reserve study | Whether the roof and road fund is real or notional |
| Minutes, two years | What the arguments are about, and what is coming |
| Assessment history | Whether special assessments are rare or routine |
The reserve study is the one people skip and the one that predicts the next bill. A development with an underfunded reserve hasn’t avoided the cost of its roads. It has postponed it, onto whoever owns there when it comes due.
And underfunded is the normal state, not the exception. Association Reserves looked at more than 100,000 reserve studies gathered between 1986 and 2025 and found that “74% of Associations within our entire reserve study data were less than 70% Funded.” Their own caveat matters and we’ll carry it: that’s their client portfolio rather than a national census, and a funding percentage doesn’t by itself predict whether a special assessment lands.
What it does tell you is that “the reserve is a bit behind” is not a warning sign. It’s the median.
Connecticut hands you these documents. New York does not
Here’s a difference between two markets we buy in every month, and almost nobody puts it in front of a buyer.
In Connecticut, the resale certificate is a statute. CGS §47-270 requires the association to give you nineteen specific items, and the list reads like it was written by somebody who had been burned:
| What Connecticut makes them disclose | Why it matters |
|---|---|
| Capital spending over $1,000 approved for this year and next | The assessment before it’s announced |
| The amount held in capital reserves | The number the reserve study argues about |
| Unpaid special assessments | What you’d be inheriting |
| Owners more than 60 days delinquent | Whether the budget actually collects |
| Foreclosures in the last 12 months | The same question, harder |
| Whether the last financial report was a compilation, review or audit | How much the numbers were checked |
They have ten business days and may charge $185. And the part that changes your position entirely: under §47-270(c), the contract is voidable until five business days after the certificate is delivered. You can walk.
New York has no equivalent that we could find. The Property Condition Disclosure Act covers the house, and its own definition excludes property in a homeowners association not owned in fee simple by the seller. It was amended in March 2024, dropping the $500 credit and going from 49 questions to 56. None of them is about the association.
So in Westchester you’re negotiating for the documents. In Fairfield County you’re entitled to them, and to a way out afterwards. That difference is worth knowing before you write an offer, and it’s the sort of thing we handle rather than leaving to the contract.
Who they suit, and who they frustrate
They suit people who want a house and have finished with the garden. Downsizers, empty nesters, buyers who travel. Anyone who has spent a decade discovering that a large lawn is a subscription, not an asset.
| The question to ask yourself | Before you look at a single kitchen |
|---|---|
| Do I want to stop maintaining a garden | Then this is the right shape of house |
| Do I want to change the outside of my home | Then the covenants will fight you every time |
They frustrate people who want to change things. If owning a house means repainting it whatever colour you like, the association will be a running argument rather than a service. One owner picked a colour from the association’s own approved list and had it rejected twice, because it “does not complement the existing stone.” The list was the rule. The committee was the decision.
It’s worth being honest with yourself about which of those you are, because the covenants won’t bend and neither will the neighbours who wrote them.
They also frustrate anyone counting on privacy from one particular side. Zero lot line means one wall of your house sits at the boundary, so the neighbour’s window may be closer than you’d choose.
Which side, and what faces it, is worth checking at the viewing. A floor plan won’t tell you, and neither will the listing.
What we see in the field
Three things come up nearly every time, and all three are in documents rather than in the house.
The dues are only half the number. Monthly association dues cover the routine. Special assessments cover the roof, the road and the pool pump, and they arrive without warning. Ask for the reserve study and the minutes of the last two years, not just the current fee.
The maintenance boundary is rarely where people assume. “The association maintains the exterior” can mean the lawn only, or the lawn and the roof, or almost everything. It’s written down, and reading that one line settles what your Saturdays look like.
Resale is narrower. A patio home appeals to a specific buyer, and in a slow market that shows. This is a live-in purchase, not a flip, and pricing it that way at the outset saves disappointment later.
Three questions settle most of it before you ever make an offer:
| Ask for | What a good answer looks like | What a bad one looks like |
|---|---|---|
| The reserve study | Funded, with a dated schedule for roof and road | “We handle that as it comes up” |
| Special assessments, five years | None, or one, explained | Several, or nobody can say |
| The maintenance boundary, in writing | A list of exactly what the association does | “They take care of the outside” |
Every buyer we represent gets the association documents read before the offer, and up to 2% of the purchase price back at closing. How that works.
Common questions
Is a patio home the same as a garden home? Usually yes. Garden home is a marketing term for the same thing, and developers use whichever sounds better in the brochure.
Do patio homes always have one storey? No, but most do, and that’s part of the appeal for buyers planning to stay put as they get older.
Is there a patio? Sometimes. The name refers to the lot arrangement rather than to a promised feature, which surprises people who came for the patio.
Do you pay HOA fees in a patio home? Nearly always, and they are the single most important number in the transaction after the price.
Are patio homes common in New York City? No. They need land and a planned development, so they belong to the suburbs, alongside terms like the FROG room that nobody uses in Manhattan.
Does a patio home count bedrooms differently? No. A single-family house follows the residential code rather than the city’s apartment rules, which is a different standard from what counts as a bedroom in the five boroughs.
Read the covenants, then the price
A patio home is a genuinely good answer to a specific question: how to own a house without owning a project. What decides whether this one is a good answer is not the kitchen. It’s forty pages of association documents that most buyers skim.
We read them for the people we represent, before the offer rather than during the attorney review. See how the buyer rebate works, or start with the full guide to apartment and house types.
Nicole Fishman Benoliel co-founded NestApple in 2017. She's a lawyer admitted to the New York bar - her law degree is from La Escuela Libre de Derecho in Costa Rica, with further study at IE Business School in Madrid and an LLM from Fordham in New York. She does not act in a legal capacity at NestApple; every client is referred to an attorney who handles real estate deals full time.